healthslips.com.au Pty Ltd (healthslips.com.au) has partnered with ItsMy Group Pty Ltd (ItsMy Group) for the provision of health insurance products. By proceeding, you agree that ItsMy Group will use your personal information for the purposes of providing advice to you on health insurance products and assisting you with arranging cover if you decide to proceed with a purchase. Not all policies can be discussed or purchased over the phone. If you click 'Talk to an expert' and our specialists cannot assist with your preferred policy, they will tell you and offer to discuss alternatives or provide you with contact details for your preferred policy.
ItsMy Group and healthslips.com.au will collect, store and use your information in accordance with the ItsMy Group Privacy Policy and the healthslips.com.au Privacy Policy.
The ItsMy Group is a signatory to the Private Health Insurance Intermediaries Code of Conduct.
If you’re in your 20s, you might find yourself considering health insurance for the first time. Maybe you:
need health cover to reduce your tax
are facing some hospital treatments
were covered by your parents’ policy and now need your own.
Whatever your situation, at healthslips.com.au we’re here to make health insurance easy to understand – what you need, how much it costs – without the jargon or sales pressure.
You don’t have to take out private health insurance in your 20s because Medicare covers you for treatment in a public hospital. But many young Australians choose it for flexibility, faster treatment and financial reasons.
Why people in their 20s get health insurance?
People in their 20s usually get health insurance for one (or more) of these reasons:
Having to leave their parents policy. (Note: some insurers allow you to remain on your parents’ policy until age 31. Check your parents’ policy for details.)
Chloe, leaving her parents’ policy Chloe is 22 and was covered by her parents’ health insurance previously. She does not want Hospital Cover because she earns $65,000 and can avoid the Medicare Levy Surcharge. She decides to get Extras Cover to cover some of her dental treatment costs.
How much does health insurance cost in your 20s?
Health insurance prices vary based on policy type (Hospital or Extras) and what’s covered – not your age.
Basic, Bronze and Silver tiers offer ‘Plus’ policies with additional services. A Basic Hospital Cover policy offers minimal cover, whereas a Basic Plus policy covers more hospital services and treatments for a little more money. If you’re considering starting a family and want to be covered for private childbirth, you’ll need to choose a policy that covers Pregnancy and Birth – which is available on a few Silver Plus policies and all Gold policies. There will be a 12-month waiting period before you can claim for childbirth, so you’ll need to take out cover before getting pregnant (find out more in our Starting a Family guide).
For a single adult, no kids, living in NSW, here are some price comparisons, as at April 2026:
Being under 30 can make you eligible for discounts that reduce your premium.
Basic, Basic Plus or Bronze Hospital Cover is usually the cheapest way to avoid the Medicare Levy Surcharge.
How much does Extras Cover cost?
Extras Cover costs less than Hospital Cover, but doesn’t reduce your tax. For a single person in their 20s, no kids, living in NSW, here are some Extras Cover price comparisons, as at April 2026:
Cheapest Extras Cover – $22.16/month, HBF Health Smart Start Extras, which covers 9 of 27 treatments including General Dental, Optical and Physio.
Combined cover includes both Hospital and Extras Cover. For a single person in their 20s, no kids, living in NSW, here are some price comparisons based on Silver tier Hospital Cover, as at April 2026:
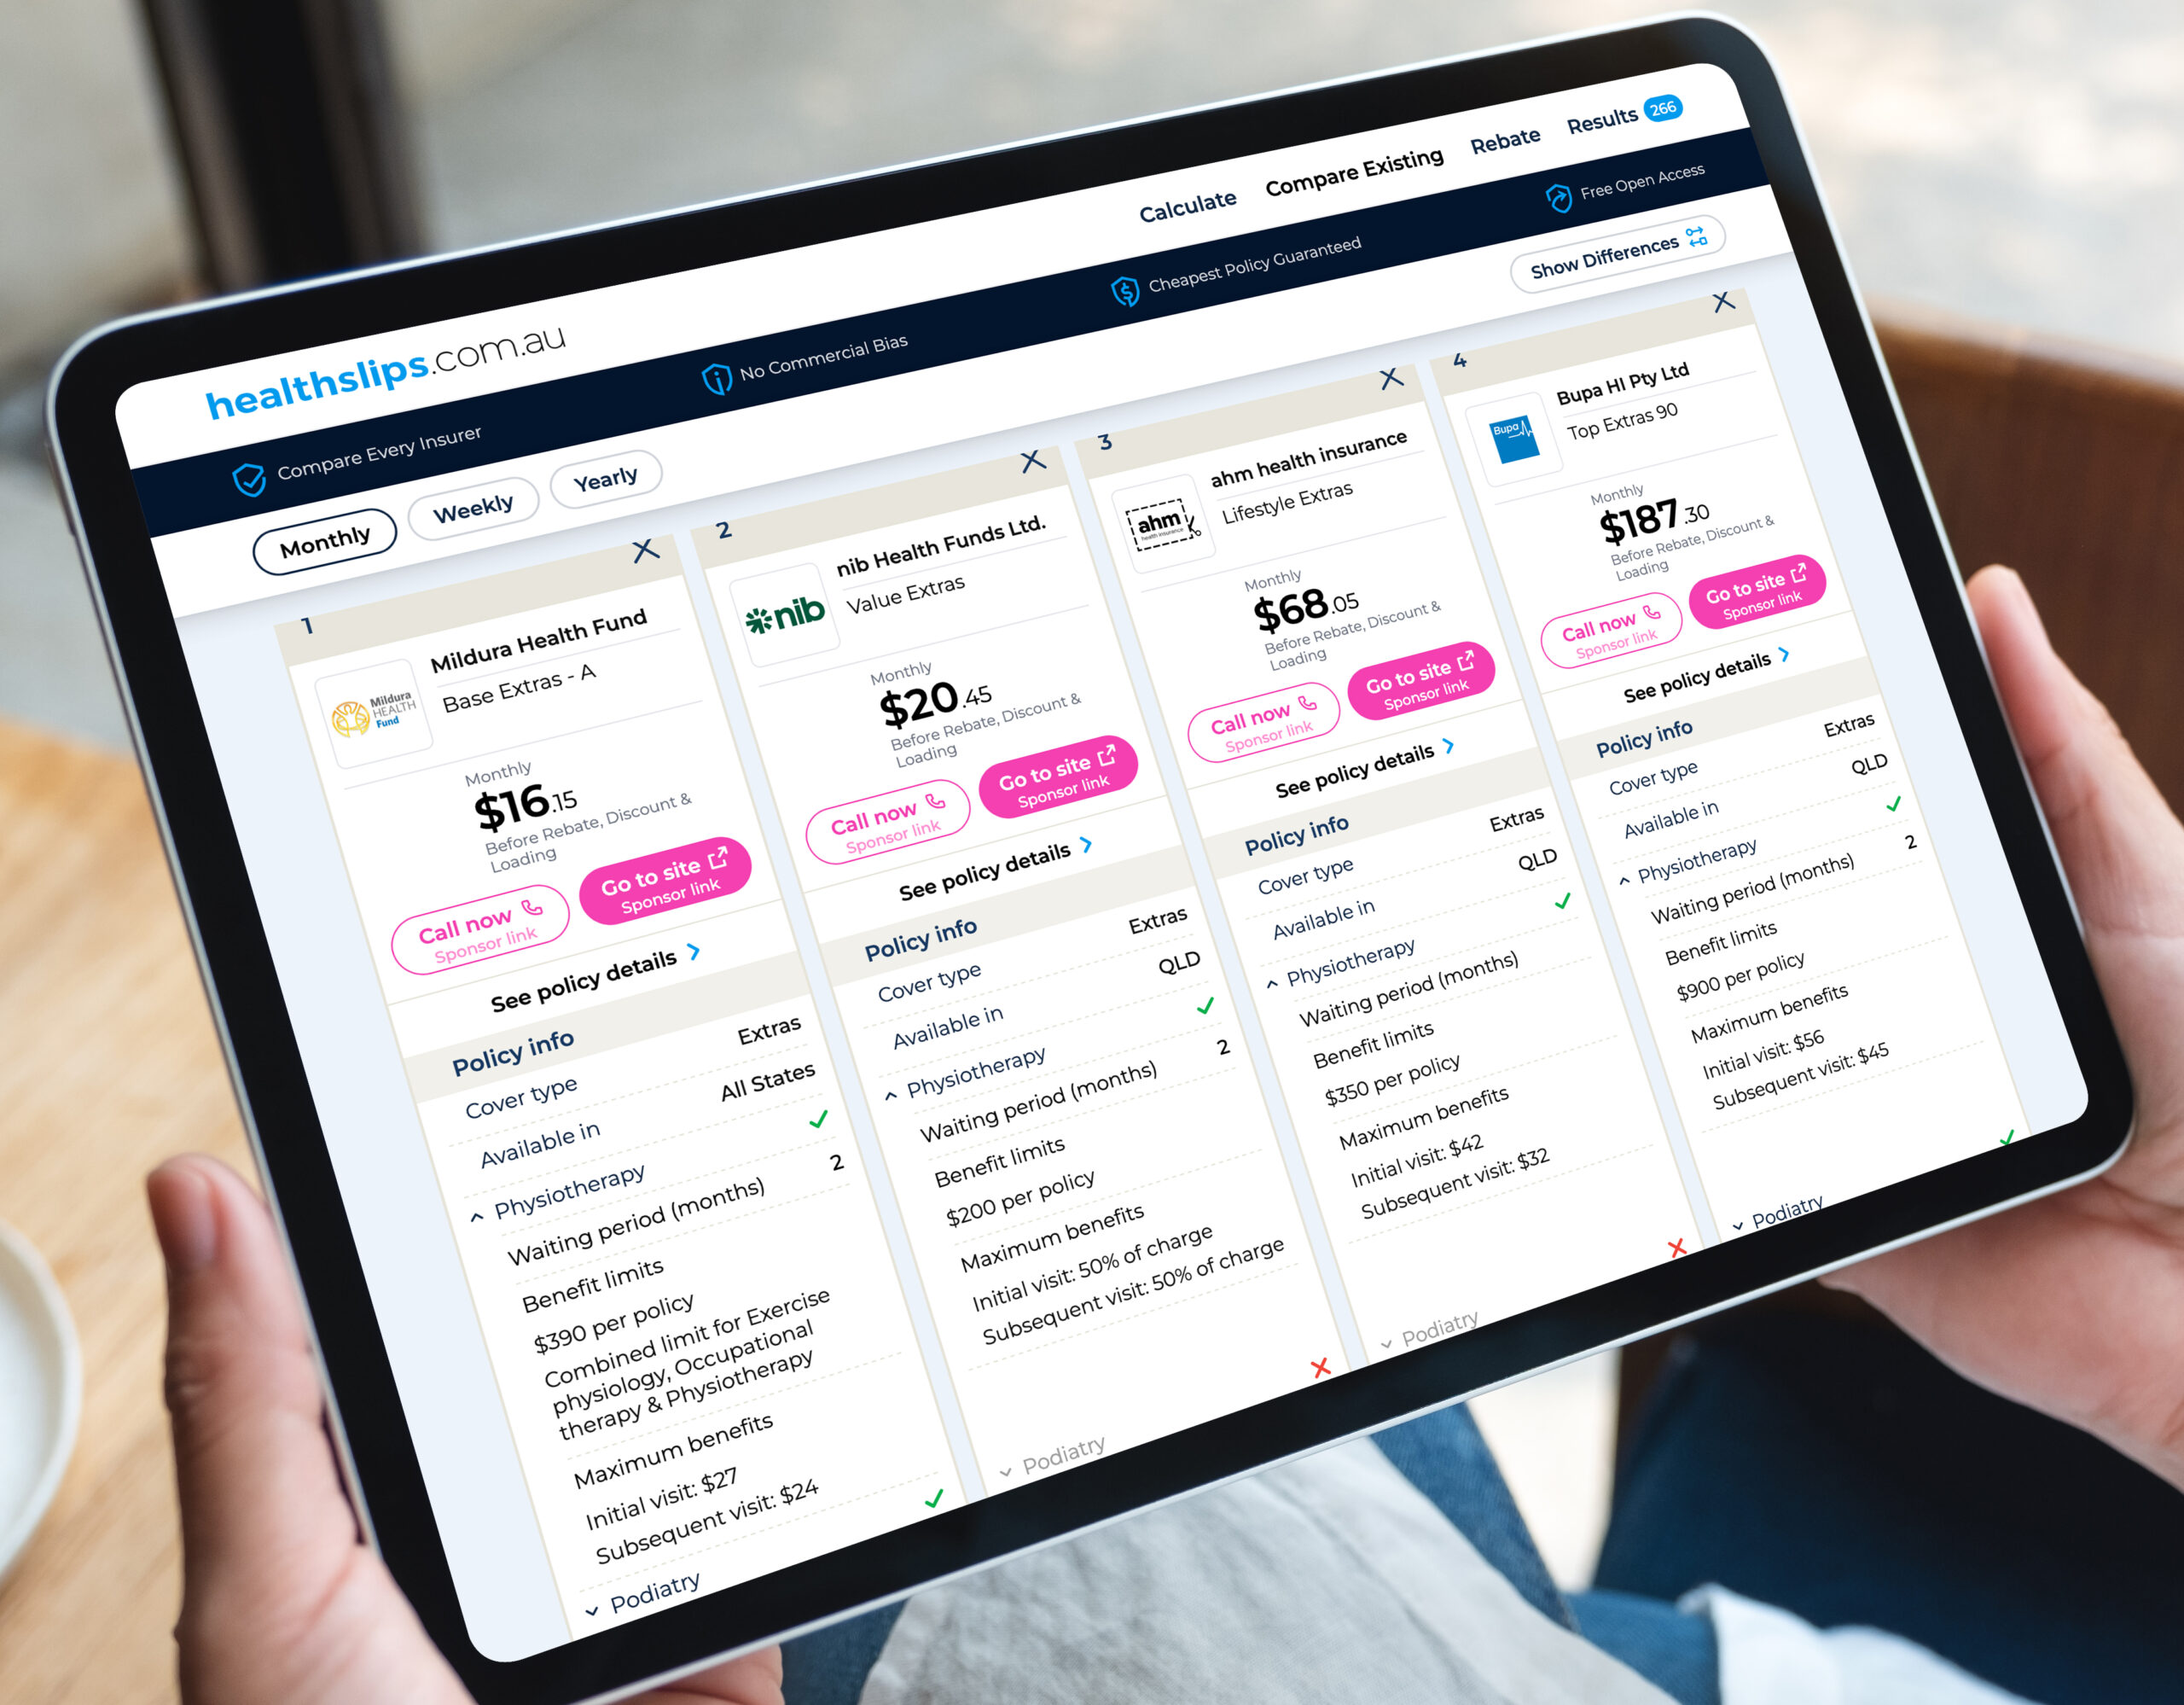
Use the healthslips.com.au calculator to compare every policy in Australia ranked cheapest to most expensive – instantly and free.
What type of health insurance should I get?
The right cover depends on what you want it for – saving tax, reducing health costs or peace of mind.
Hospital Cover – covers the cost of treatment in a private hospital, or as a private patient in a public hospital. Hospital Cover helps you get non-urgent surgery faster, choose your own doctor and get your own room (if available). Hospital Cover helps you avoid paying the Medicare Levy Surcharge if your income is over the MLS threshold.
Extras Cover – helps cover the cost of a range of treatments that Medicare does not cover, such as dental, physio, optical and psychology. Extras Cover doesn’t cover all of your treatment cost and there’s an annual limit. Keep in mind: Extras Cover does not affect the Medicare Levy Surcharge.
Combined Cover – includes Hospital Cover and Extras Cover.
Ambulance Cover – Medicare doesn’t cover ambulance treatment, but if you have Ambulance Cover your ambulance treatment costs are covered. Ambulance treatment is often included with Hospital Cover and Extras Cover policies, so you may not need Ambulance Only Cover if you have other health insurance. (Note: not required for QLD or TAS residents because your state governments fund ambulance costs.)
Couple – covers 2 adults in a relationship, living together (you don’t have to be married)
Single Parent – covers one adult and one or more children.
Family – covers 2 adults in a relationship, living together, with one or more children.
Compare all cover types and the cost of including a partner and children in your policy using the healthslips.com.au calculator. It’s fast, easy and free.
Jade & Kim, different health needs Jade, 27, and Kim, 28, are a couple who have lived together for a year. They want to get Hospital Cover so they can avoid paying the Medicare Levy Surcharge. Jade has type 1 diabetes and wants cover for insulin pumps, but Kim doesn’t need a high level of cover, so they decide to get 2 Singles policies. Jade buys a Gold tier policy to cover her insulin pumps, while Kim buys a Basic Plus policy to give her a basic level of cover.
Essential to know
If you’re under the age of 31 and single, you may be eligible for cover on your parents’ policy. Check your parents’ health insurance policy for details.
Incentives and penalties to know in your 20s
Government incentives can significantly affect how much you pay, especially if you buy Hospital Cover before turning 31.
Government Rebate – reduces your health insurance premium based on your income and number of children. Check your eligibility.
Age-based Discount – reduces your Hospital Cover premium if you start cover before 30, and if you maintain your policy, you may keep the Discount until the age of 41. Not available from all insurers. Check details here.
Lifetime Health Cover Loading – increases your Hospital Cover premium if you don’t take out cover before the age of 31. It’s a good reason to consider taking out a policy in your 20s. Get all the details here.
Also remember the Medicare Levy Surcharge (MLS), which isn’t a penalty – it’s a type of tax if you earn more than $105,000 (as a single person). It applies to anyone earning over a certain income level who doesn’t have Hospital Cover.
Tim, wants to avoid the MLS and Loading Tim is 28 and earns $110,000. He decides to get Hospital Cover so he can avoid the Medicare Levy Surcharge, and avoid the Lifetime Health Cover Loading by buying cover before he turns 31. He is planning to move to the UK next year for 2 years so will cancel his policy and buy a new policy when he returns to Australia.
Liam, plays competitive footy Liam is 28, plays competitive footy regularly. He knows he’s at higher risk of injury but decides he’s happy to be treated in the public hospital system. His income is $80,000 so he doesn’t have to pay the Medicare Levy Surcharge. He decides to wait until his 30s to get health insurance.
How do I choose health insurance in my 20s?
Here are the 4 easy steps to choosing a health insurance policy in your 20s:
Choose your type of cover If you want to avoid the Medicare Levy Surcharge, you’ll need Hospital Cover. If you want cover for out-of-hospital treatments like dental and physio, you’ll need Extras Cover. Choose Hospital Cover, Extras Cover or both, based on your health needs and budget.
Choose what treatments you need covered If you have a health condition, or a family predisposition to a particular illness, look for a policy that meets those needs.
Search for the cheapest policy that meets your needs and budget With the free healthslips.com.au calculator, you can search every policy in Australia without commercial bias, and we guarantee you the cheapest policy. See your results instantly without entering your name, email or phone number.
Buy your policy Once you’ve found the right policy, double-check the details – including waiting periods and excess. You’ll be covered as soon as you’ve paid your first premium, but there may be waiting periods before you can claim.
Angie, planning for surgery Angie is 24 and has been diagnosed with endometriosis. Her doctor has told her she may need surgery in the future and there could be a long wait in the public system. She buys a Bronze Hospital Cover policy that includes the Gynaecology clinical category. Although there is a 12-month waiting period for pre-existing conditions, she is happy to wait as she will likely not need surgery in the next year.