healthslips.com.au Pty Ltd (healthslips.com.au) has partnered with ItsMy Group Pty Ltd (ItsMy Group) for the provision of health insurance products. By proceeding, you agree that ItsMy Group will use your personal information for the purposes of providing advice to you on health insurance products and assisting you with arranging cover if you decide to proceed with a purchase. Not all policies can be discussed or purchased over the phone. If you click 'Talk to an expert' and our specialists cannot assist with your preferred policy, they will tell you and offer to discuss alternatives or provide you with contact details for your preferred policy.
ItsMy Group and healthslips.com.au will collect, store and use your information in accordance with the ItsMy Group Privacy Policy and the healthslips.com.au Privacy Policy.
The ItsMy Group is a signatory to the Private Health Insurance Intermediaries Code of Conduct.
Whether you’re fit and healthy or you’re facing hospital treatments, there are lots of reasons to consider health insurance in your 30s. Maybe you want to:
avoid extra tax as your income grows
plan ahead for surgery or ongoing health needs
start (or grow) a family
protect your health as you get older.
Whatever your reason, we’re here to help you understand your options, compare costs and choose health insurance that fits you – without the jargon or sales pressure.
Access private childbirth options (find out more in our Starting a Family guide).
Priya, planning ahead Priya is 34 and regularly runs marathons. She already has Extras Cover to reduce her physio and massage costs, but decides to get Hospital Cover as well, in case she experiences any injuries that need surgery. Hospital Cover will allow her to have the procedure done in a private hospital and get back to training faster.
How much does health insurance cost in your 30s?
The cost of health insurance depend on what’s covered, not your age.
There are 4 Hospital Cover tiers: Basic, Bronze, Silver and Gold. Also available are ‘Plus’ policies (in Basic, Bronze and Silver) which cover more treatments.
For a single adult in their 30s, no kids, living in Queensland, here are some price comparisons as at April 2026:
The Lifetime Health Cover Loading adds 2% to your Hospital Cover premium for every year you’re over 30 when you first take out cover (removed after 10 years of continuous cover).
How much does Extras Cover cost?
Extras Cover helps reduce the cost of services outside hospital, like dental, physio and optical. It does not reduce your tax. For a single person in their 30s, no kids, living in Queensland as at April 2026:
Cheapest Extras Cover – $22.73/month, HBF Smart Start Extras, which covers 9 of 27 treatments including General Dental, Optical and Physio.
Combined Cover includes Hospital and Extras cover. For a single adult in their 30s, no kids, living in Queensland, here are some price comparisons for Bronze Hospital tier, as at April 2026:
Cheapest Combined Cover – $154.35/month, $750 excess, Frank Health Insurance Bronze Hospital & Bundables $250, which covers 21 of 38 Hospital Cover clinical categories and 13 of 27 Extras treatments including General Dental, Optical and Physio.
The right cover depends on what you want it for – saving tax, reducing health costs or peace of mind.
Hospital Cover – covers treatment in a private hospital or as a private patient in a public hospital and can help you access non-urgent surgery faster. It helps you avoid the Medicare Levy Surcharge if your income is over the MLS threshold. It can also help you access private childbirth, although there’s a 12-month waiting period so you’ll need to buy your policy before getting pregnant (find out more in our Starting a Family guide).
Extras Cover – helps cover out-of-hospital costs not covered by Medicare such as dental, physio, optical and psychology. Extras Cover doesn’t cover all of your treatment costs and there’s an annual limit. Remember that Extras Cover does not affect the Medicare Levy Surcharge.
Combined Cover – includes Hospital Cover and Extras Cover. It won’t save you any money, but it means you’ll only have one bill to pay for 2 types of insurance.
Ambulance Cover – Medicare doesn’t cover ambulance treatment, which is why Ambulance Cover can be useful. Ambulance treatment costs are often included with Hospital Cover and Extras Cover policies, so you probably won’t need Ambulance Only Cover if you’re buying other health insurance. (Note: if you live in Queensland or Tasmania, your state governments fund ambulance costs.)
Family – 2 adults and one or more children (you don’t have to be married).
Compare all cover types and the cost of including a partner and children in your policy using the healthslips.com.au calculator. It’s fast, easy and free.
Becky & Alex, different priorities Becky, 31, and Alex, 33, are a couple who live together. Becky has got a promotion that will put her salary over the Medicare Levy Surcharge threshold, while Alex has been told they will need surgery for plantar fasciitis in the next few years. Alex gets a Silver tier Singles policy so they can have their surgery in a private hospital once they have served the 12-month waiting period for pre-existing conditions. Becky gets a Basic Plus Singles policy that gives her a lower level of cover but means she avoids the Medicare Levy Surcharge.
Incentives and penalties to know in your 30s
Government incentives and penalties can significantly affect how much you pay for health insurance:
Private Health Insurance Rebate – reduces premiums if you earn below the income thresholds.
Lifetime Health Cover Loading – adds 2% to Hospital Cover premiums for every year you’re over 30 when you first take out cover (removed after 10 years of continuous cover).
Don’t forget about the Medicare Levy Surcharge (MLS) – an extra tax (1-1.5% of income) that applies if you earn over the threshold and don’t have Hospital Cover for the full financial year.
Dev & Bella, starting later Dev, 38, and Bella, 36, are a couple who live together. They decide to buy a Hospital Cover policy in case they need private hospital treatment in the future. Because neither has had Hospital Cover before, they each must pay Lifetime Health Cover Loading – Bella 10% and Dev 16%. They buy a Couples policy which includes a Loading of 13% – the average of Dev and Bella’s individual Loadings.
Image credit: Shutterstock
How do I choose health insurance in my 30s?
Here are 4 simple steps:
Choose your cover type If you want to avoid the Medicare Levy Surcharge, you’ll need Hospital Cover. If you want cover for out-of-hospital treatments like dental and physio, you’ll need Extras Cover. Choose Hospital Cover, Extras Cover or both, based on your health needs and budget.
Choose what treatments matter If you have a health condition, or a family predisposition to a particular illness, look for a policy that meets those needs.
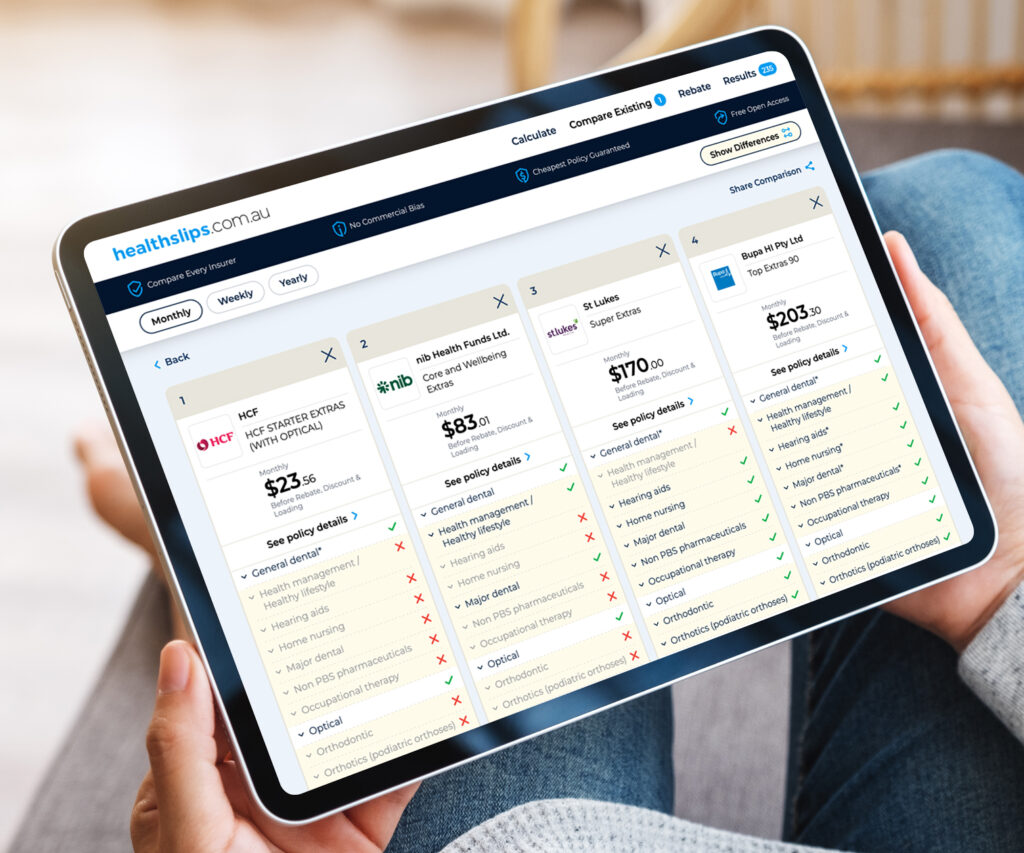
Compare policies With the free healthslips.com.au calculator, you can search every policy in Australia without commercial bias, and we guarantee you the cheapest policy.
Buy your policy Check waiting periods, excess and any incentives or penalties before buying. You’ll be covered once you’ve paid your first premium, but there may be waiting periods before you can claim.
Oliver, planning for prevention Oliver is 33 and has a family history of bowel cancer. He considers a Bronze tier Hospital Cover policy that includes the Gastrointestinal Endoscopy clinical category so that he can get colonoscopies done at a private hospital, avoiding public hospital wait times. He decides to get a Combined Hospital and Extras policy so he can also claim for dental and physio treatments. He has to pay 6% Lifetime Health Cover Loading which increases his policy price, but because his income is in the lowest income bracket for the Private Health Insurance Rebate, his premiums are reduced.